by SpringFour | Feb, 11, 2013 | Default, Post - Insights
We read with interest The Wall Street Journal’s recent article on Fifth Third Bancorp. Seems that the enterprising folks at Fifth Third Bank are expanding a job coaching program that offers training for homeowners who have fallen behind on their payments. It specifically targets delinquent homeowners who have lost their job or had a significant drop in their income.
The tiny pilot program was quite a success. Eleven of the 28 participants found jobs after 6 months. Best of all, none of the participants were foreclosed upon, although Fifth Third maintains that they kept “the foreclosure clock” running.
Here at MortgageKeeper, our data consistently points to the need struggling homeowners have for job assistance. It is consistently one of the top three needs of folks who don’t know how they will make their next mortgage payment. To paraphrase the old saying: Giving a homeowner a loan modification will help decrease his payments, but teaching a homeowner to find stable employment will help them never to be delinquent again.
MortgageKeeper has many mortgage servicer clients who provide employment and other support to their borrowers, using our products to help delinquent homeowners get to the root of their financial problems and find a way to make their financial picture whole again. We look forward to hearing more of Fifth Third’s successful program
by SpringFour | Jan, 29, 2013 | Default, Post - Insights
A childhood friend of mine recently posted the following on Facebook:
“I was listening to NPR’s Marketplace weekend show, and there was a piece on renting versus buying a home. The generation after ours has seen how the housing bubble burst, and they’re tending to rent with no plans to ever buy a house/condo. Any opinions? As for us, we bought our house at the height of the bubble and then watched it lose almost $30K in value in one year. We’re slowly gaining equity again, but we certainly didn’t expect this to happen.”
She has racked up 23 comments and counting. The opinions are all over the board:
A responsible landlord is like gold!”
I too bought at the height of the bubble and over the last few years I’ve lost $50K in value. I wish I had rented instead. I love the flexibility of renting. Owning is an elaborate set of leg irons.”
“…we’ve watched [our house] lose almost a third of its “value”. But, the thought of ever renting from someone again—bleah.”
We have been very hesitant to buy. I’m sure my parents were in their 2nd home when they are 30! Real estate doesn’t seem like the “investment” it used to be. Also, our generation moves more and “settles down” later than the preceding generation and owning a home “ties” one down.”
One post cited a calculator from The New York Times to help determine if you should buy or rent. But perhaps this is too big of a question to be determined by a newspaper logarithm.
Did you buy or do you rent? And do you stand by your decision?
![The Service We Offer That Hopefully Goes Unused]()
by SpringFour | Jan, 16, 2013 | Default, Post - Insights
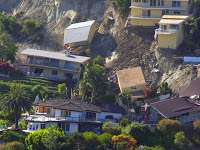
If you are familiar with MortgageKeeper, you know that we offer 20+ categories where folks can find help to their personal and financial crises. From prescription drugs to property tax, child care to credit counseling, we have it pretty well covered.
That is, except for disaster relief services.
We only began seriously considering this category in the last year or so. But after Hurricane Sandy, it seems like a wise and prudent move to offer our clients a means to refer their callers or online users to the most up to date relief available to them during a crisis.
We’re sure hoping that a disaster relief category gathers a lot of dust. But it will be there if it’s needed.
by SpringFour | Jan, 3, 2013 | Default, Post - Insights
We here at MortgageKeeper are jumping on the resolution train. To have a look at getting our finances in order, we welcome Karen Carlson, Director of Education for one of our newest clients, InCharge Debt Solutions, as our guest blogger.
Top Five Money Resolutions for 2013
By Karen Carlson, Director of Education at InCharge Debt Solutions
Looking to shore up your finances this year? Become in charge of your money with resolutions you can take to the bank.
1. Pay off your credit card debt. If you are among the nearly 40% of Americans who carry credit card debt from month to month, it’s time to kick the habit and pay it off. If your total debt is less than 15% of your annual income, you should be able to pay it off in one year. Divide the amount owed by the number of paychecks you receive in a year. Pay your debt payments first, on payday.
2. Build an opportunity fund. Typically called the emergency fund, we like to cast money stashed away ‘just in case’ in a positive light. What opportunities could you take advantage of in 2013 or 2014 if you had money saved? Where could you go? What experiences could you have? Set up direct deposit from your paycheck to your savings account and put
your money where your dreams are in 2013.
3. Stop living paycheck-to-paycheck. What’s worse than working 40 hours a week for 10 years with nothing to show for it? Working 40 hours a week for 20 years with nothing to show for it. In fact, a large percentage of baby boomers have worked the majority of their adult lives and have accumulated little in the way of assets. Paycheck-to-paycheck living will rob you of the ability to save, invest and retire with dignity. Learn how to live with less. Be creative. Draw a line in the sand and find room in your budget this year.
4. Grow Your Income. As the unemployment rate drops, there will be more opportunities to work longer hours or pick up a second job. But recognize that the US job market is in the middle of a dramatic shift, toward jobs that require higher education and greater technological skill. Get educated. Get certified. Improve your income potential and employability, even if it means a temporary pay cut. Consider creating a job by starting a small business.
5. Reach Out When You Need Help. If you’re struggling financially and you need help, all you have to do is ask. Reputable nonprofit organizations are standing by to help you analyze your financial situation, make a budget and illuminate a path to stability. These include InCharge—who also make referrals using the MortgageKeeper data application to find local agencies that can help.
Making a resolution is the first step, but sticking to it can be difficult. Behavior change research shows that successful resolutions are followed by detailed action plans. This means committing to your resolution to writing, breaking it down into small ‘bite-sized’ goals (weekly milestones, for example), and tracking your progress. It’s okay to have a slip-up, but get back on your plan as soon as possible.
Good luck and Happy New Year.
by SpringFour | Dec, 17, 2012 | Default, Post - Insights
Ah yes. There’s no place like home for the holidays. Many of us are cautiously optimistic that more struggling homeowners will be able to stay in their homes in 2013.
Why the glass-half-full thoughts? Foreclosure prevention efforts are making their mark. Reports hint that more jobs are out there. Foreclosure starts are at a 71-month low.
What keeps the glass only half full are some stats that give us pause…including some of our own. MortgageKeeper referrals are up–way up–at the end of this year. This is due to several factors, but also shows us that help is still needed. Stats from RealtyTrac show that bank repossessions are on the rise. So perhaps we’ve just been enjoying a foreclosure “holiday” while changes in servicing and foreclosure policies are implemented. As with all statistical information, time will tell if we are all-knowing or all wet.
From all of us at MortgageKeeper, we wish you the very best of holidays, and hope that 2013 brings more relief and assistance for those struggling to keep their homes.
by SpringFour | Dec, 11, 2012 | Default, Post - Insights
Mistakes are the portals of discovery. ~ James Joyce.
Ah yes, mistakes. We all make them. We hate them–especially their inevitability. But even the most negative of folks know that they don’t leave us where they found us.
So it goes with the Housing Crisis. No matter what your politics, if you are servicer or foreclosure counselor, struggling homeowner or landlord, we can agree that the mortgage and housing markets needed to be repaired.
A recent article in The New York Times made us think about housing system flaws that are coming to the forefront. It discusses how a Catch 22 is sending quite a few widows into untimely foreclosure: these women can’t get help lowering their payments until they are named on the mortgage note…but they can’t add their name until they are current on payments.
No doubt surviving spouses have been battling this issue for years. However, it took the Housing Crisis, the focus on foreclosure, and the sheer number of victims to cause consumer advocacy groups and even some heavy hitters in the mortgage servicing industry to take notice. And change, while perhaps slow to come, is coming. Crisis always leads to opportunity.

Recent Comments